You cannot pay for months before applying to join Japan’s Small Enterprise Mutual Aid scheme. Official guidance does, however, describe a joining-month contribution plus 12 prepaid months (13 in total), and an existing member paying the current year plus the next year in advance. At ¥70,000 a month, those examples produce ¥910,000 and ¥1,680,000 of income deductions. They do not produce refunds of those amounts.
Sources and deadlines were checked on November 5, 2026. All official source links below are in Japanese.
Previous-year payments and advance payments are different
SMRJ FAQ681 states:
加入申込月の前月以前の掛金は納付することはできません
This means contributions cannot cover months before the application month. A new member cannot join now and pay for last year to reduce last year’s income.
Paying arrears under an existing contract is a different situation. FAQ881 explains that contributions actually paid during a calendar year are deductible for that year. Paying last year’s overdue contribution now does not turn it into a payment made last year.
Joining month plus 12 prepaid months: 13 in total
SMRJ FAQ724 explicitly describes the application payment plus 12 months paid in advance. Its statement includes:
合計13か月分の掛金全額がその年の所得控除の対象
In other words, all 13 months in this example qualify for the payment year’s deduction. At ¥70,000 a month, the total is ¥910,000.
Paying 13 months in total is different from prepaying 13 future months. The same FAQ distinguishes advance payments of 13 months or more. FAQ69 explains the treatment of prepayments exceeding one year: do not assume the entire amount becomes immediately deductible; the portion allocated to the current year matters.
The ¥1.68 million example is for an existing member
SMRJ’s J-Net21 explains a current-year ¥840,000 contribution plus one following year paid in advance, using:
840,000円×2年=1,680,000円
The J-Net21 article was last updated on March 31, 2018. We use it for the stated payment example, together with the current FAQ67 on prepaying up to 12 months. We do not reuse its old tax calculation table.
For an existing monthly-paying member who has not already prepaid next year:
| Payments actually made this year | Amount |
|---|---|
| January–November of the current year | ¥770,000 |
| December of the current year | ¥70,000 |
| January–December of the following year, prepaid | ¥840,000 |
| Total paid this year | ¥1,680,000 |
This combines the current year’s ordinary payments with one following year. It does not mean paying for a year before joining or immediately deducting any arbitrary 24 future months. Other circumstances, such as arrears, exist, so ¥1.68 million is not presented as an absolute statutory ceiling.
The same contribution cannot be deducted again the next year. Bringing a deduction forward does not create an extra annual allowance of ¥1.68 million forever.
How much tax does the deduction save?
National Tax Agency No.1135 describes an income deduction. It reduces taxable income. It is not an equal-sized tax credit, a business expense or a corporate expense.
The following examples assume income-tax and resident-tax taxable income of ¥4 million each, after other deductions but before this contribution deduction. They use the 2026 income tax and reconstruction surtax rules, and a resident income levy of 6% municipal plus 4% prefectural tax, each rounded down to ¥100. Tax credits, withholding, advance tax payments and local variations are excluded. Sources: national tax rates, national rounding and resident tax calculation.
| Confirmed example | Income deduction (JPY) | National tax relief (JPY) | Resident tax relief (JPY) | Total relief (JPY) |
|---|---|---|---|---|
| Ordinary 12 months | 840,000 | 157,300 | 84,000 | 241,300 |
| Joining month + 12 prepaid months (13 total) | 910,000 | 164,400 | 91,000 | 255,400 |
| Existing member: current 12 + next 12 months | 1,680,000 | 243,000 | 168,000 | 411,000 |
These examples assume no prepayment reduction payment received in that year. If you receive one, SMRJ’s guidance requires subtracting it from the year’s contribution deduction. Resident tax relief generally affects the following fiscal year; the total is not a promise of a cash refund before December.
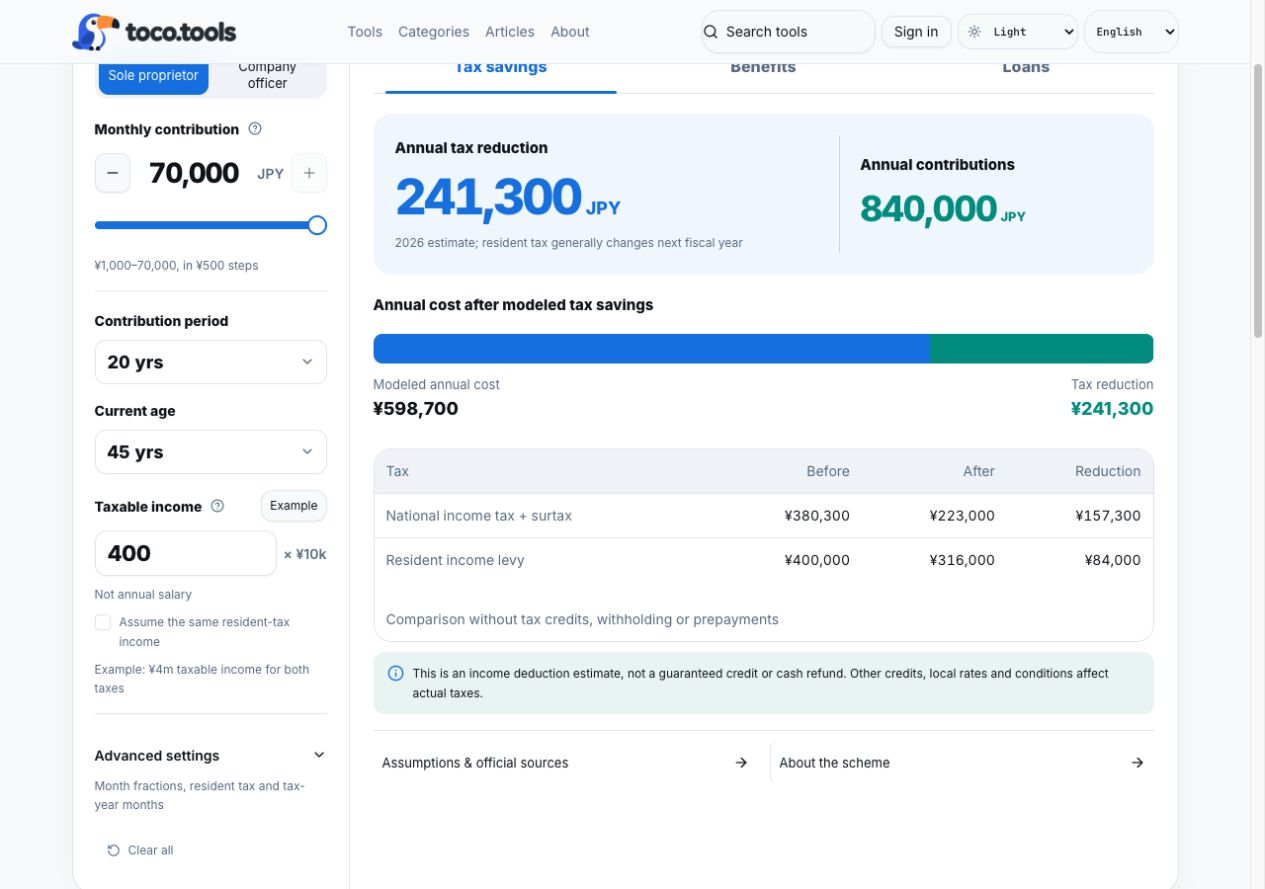
This screenshot shows the ordinary 12-month ¥840,000 baseline. To reproduce it in the mutual aid simulator, enter ¥70,000 monthly and use the taxable-income example button. The current screen accepts 1–12 paid months for its ordinary-year model. The ¥910,000 and ¥1,680,000 prepayment cases above use the shared annual tax calculation after separately confirming deductibility; they are not results obtained by entering 13 or 24 months in the screen.
Does front-loading always reduce two years’ total tax?
A larger deduction this year does not necessarily minimize tax over two years. Suppose taxable income is ¥4 million in both years, with the 2026 tax rules and all other conditions held unchanged. Compare the same ¥1.68 million of contributions:
| Payment schedule | Year 1 relief | Year 2 relief | Two-year relief |
|---|---|---|---|
| ¥840,000 in each year | ¥241,300 | ¥241,300 | ¥482,600 |
| ¥1,680,000 in year 1; no additional payment in year 2 | ¥411,000 | ¥0 | ¥411,000 |
Front-loading saves ¥71,600 less in this particular example because the deduction spans different marginal tax brackets. Different income in the two years can change the result. Prepaying also uses cash earlier, so next year’s deductions and working-capital needs matter.
Important deadlines for the end of 2026
An SMRJ notice dated October 16, 2026 states that online joining applications in November and December do not qualify for a 2026 deduction, because the initial debits occur in January and February 2027. Online applications qualifying for 2026 therefore stop with October applications. Merely applying before December 31 is insufficient. The notice directs people joining in November or December who seek a current-year deduction to the applicable cash-payment process at a service counter. Confirm eligibility, acceptance and processing dates there.
For an existing member requesting a December lump-sum prepayment by bank debit, the payment procedure specifies documents arriving at SMRJ by November 20, or completion online before 24:00 that day. This is a different deadline from the online joining application cutoff.
An announcement dated September 10, 2026 also describes a planned January 1, 2027 revision, with cash contribution payments scheduled to end in December 2026 and bank debit becoming the general method. A procedure available at the end of 2026 should not be assumed available in 2027. Check the latest notice when applying.
Before paying
- Distinguish periods before joining, arrears under an existing contract and future prepayments.
- Confirm the amount actually paid within the year, rather than relying only on the application date.
- Check whether advance payments exceed 12 months and whether you received a prepayment reduction payment.
- Compare this year and next year’s income, deductions and cash needs.
For the broader joining decision, read our comparison with NISA investing, benefit amounts and borrowing.